

When most investors open a rental property pro forma, the first question is usually pretty simple: What return does this property show?
Naturally, that’s where our eyes go first.
But after looking at a lot of pro formas over the years, one thing has become clear: the return at the top is really only the starting point.
On last week’s Not Your Average Investor Show, we pulled apart a real rental property pro forma that looked polished and convincing at first glance. What we discovered: it’s surprisingly easy to “juice” a pro forma. A small change in where an expense is counted or when a projected gain shows up can make the return at the top look dramatically different.
Let’s dive in.
What’s Under The Headline Return?
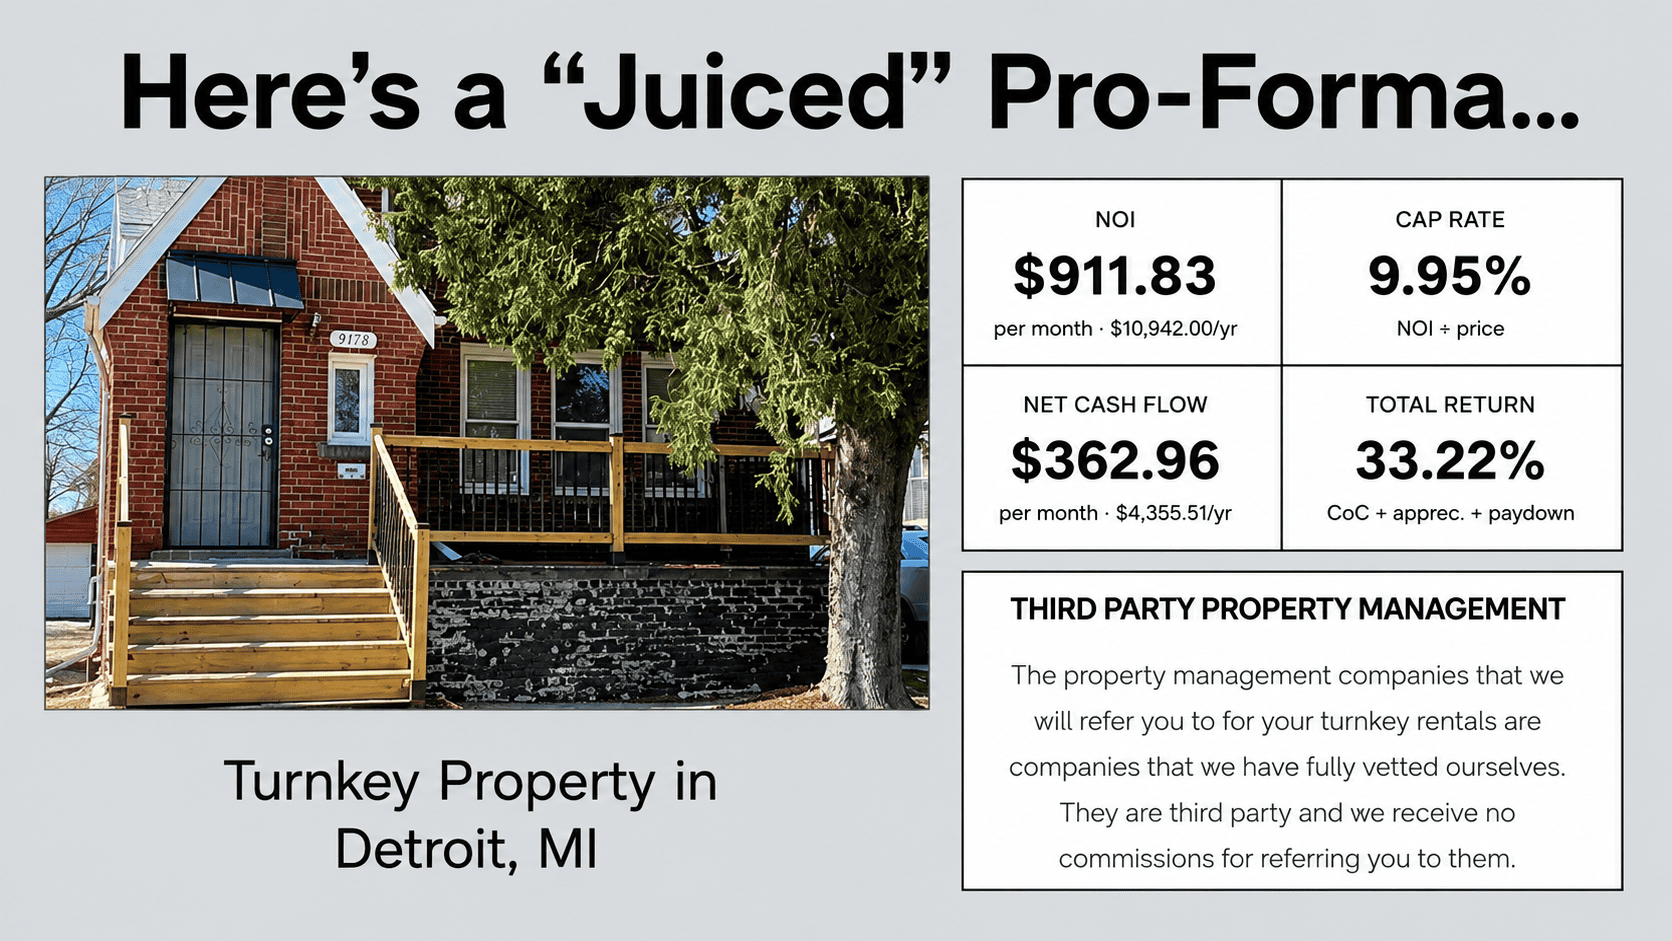
The pro forma above showed a 33.2% projected return and about $363 in monthly cash flow. So the next step was simply to follow where that return came from.
One thing that stood out was maintenance and vacancy. The sheet listed 5% for maintenance and 5% for vacancy, which sounded reasonable. But both appeared below the net cash flow line, meaning they were visible without actually reducing the cash flow being used in the return.
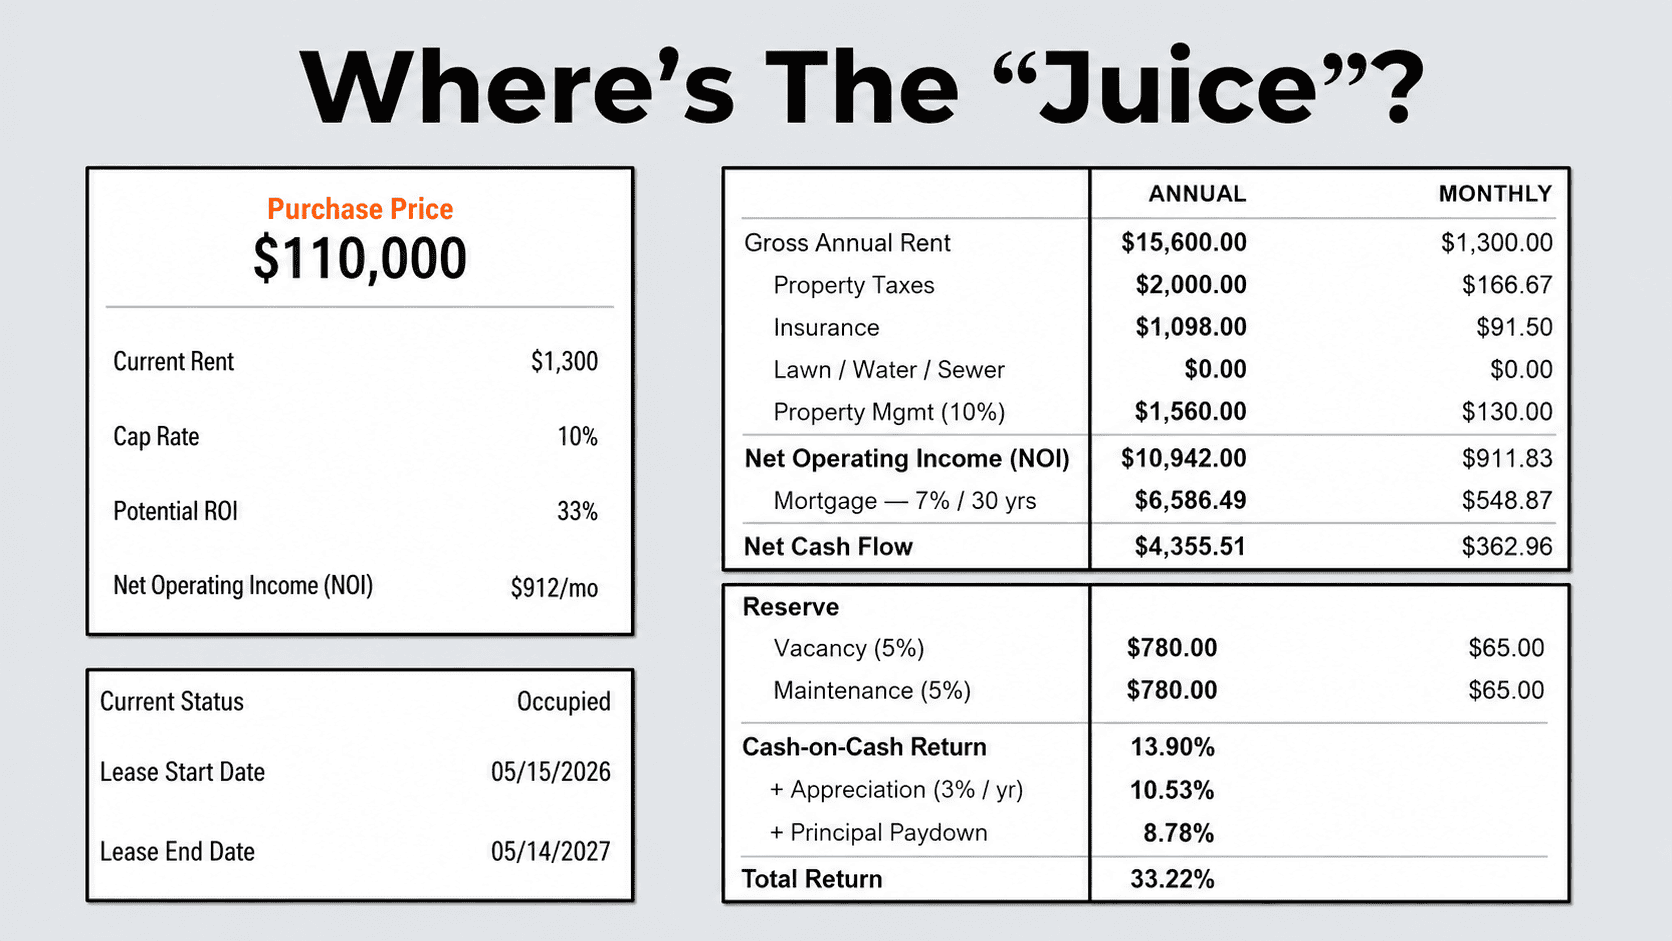
Something similar showed up with principal paydown. The sheet showed an 8.78% return from principal paydown, but when we checked the stated loan against the actual payment schedule, the first year principal reduction was closer to $838, or about 2.7% of the cash invested from that source. It also shouldn’t have been factored into the year 1 return as you do not realize the reduction of principal in your bank account until you sell the property.
That is why seeing an assumption somewhere on the page is not enough. It helps to understand how that assumption actually affects the return.
And once we start following the numbers that way, another question becomes important: When does that value actually become available?
When Does The Money Actually Show Up?
The biggest issue was not that the property was expected to appreciate. It was when that appreciation was being counted.
About 10.5% of the projected year one return came from home price appreciation, even though that value was still sitting in the property until you sell or refinance.
👇 The mistake that changes a pro forma return
If the model assumes the property is sold in year 10, it makes more sense for that value to be reflected when it is expected to be accessed in the model. And if selling is how that happens, selling costs should be part of the picture too.
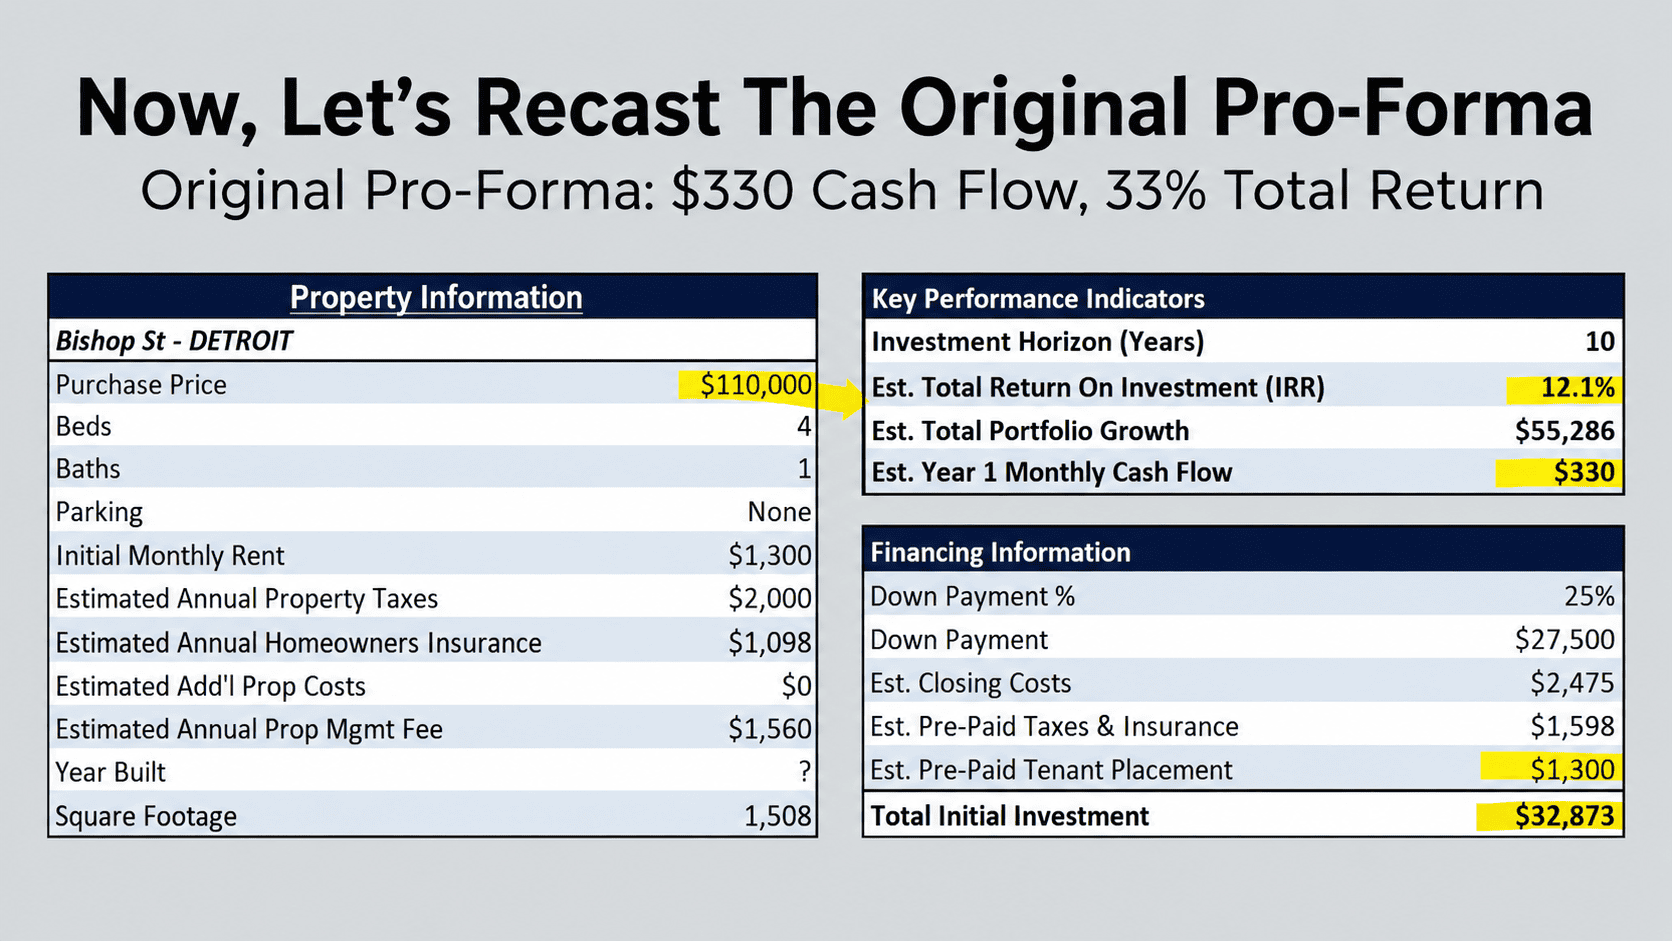
Once we rebuilt the pro forma with assumptions we felt were more supportable and adjusted for when those gains were counted, the projected return moved from 33.2% to about 12.1%.
Same property. The difference was how the story was being told through the numbers.
That is why timing matters. If a benefit is being counted in a projection, the useful question becomes: When is it expected to become available, and what has to happen for the investor to receive it?
But even after the math and timing are cleaned up, there is still one more question:
How do you know whether the assumptions themselves are reasonable?
The Three Numbers to Separate First
When reading a pro forma, it helps to sort the numbers into three simple groups.
- What we know today: These are things like purchase price, starting rent, mortgage payment, financing terms, insurance, and the initial cash needed.
- What the operator should know: This includes maintenance, vacancy, resident stays, and property turns. These are still estimates, but they should be tied to actual operating history.
- What the market will decide: Future rent growth and home price appreciation fall into this group.
Nobody knows those numbers exactly, so longer-term historical data can be more useful than picking a recent period that happens to make the projection look better. In this example, we used Jacksonville’s long-term historical home price appreciation of about 4.8% per year.
👇 How to read rental pro forma assumptions
The operator assumptions are especially important because this is where real experience can make the projection more useful.
For example, JWB renters stay an average of 4.5 years so we built our pro-forma model with those numbers in mind.
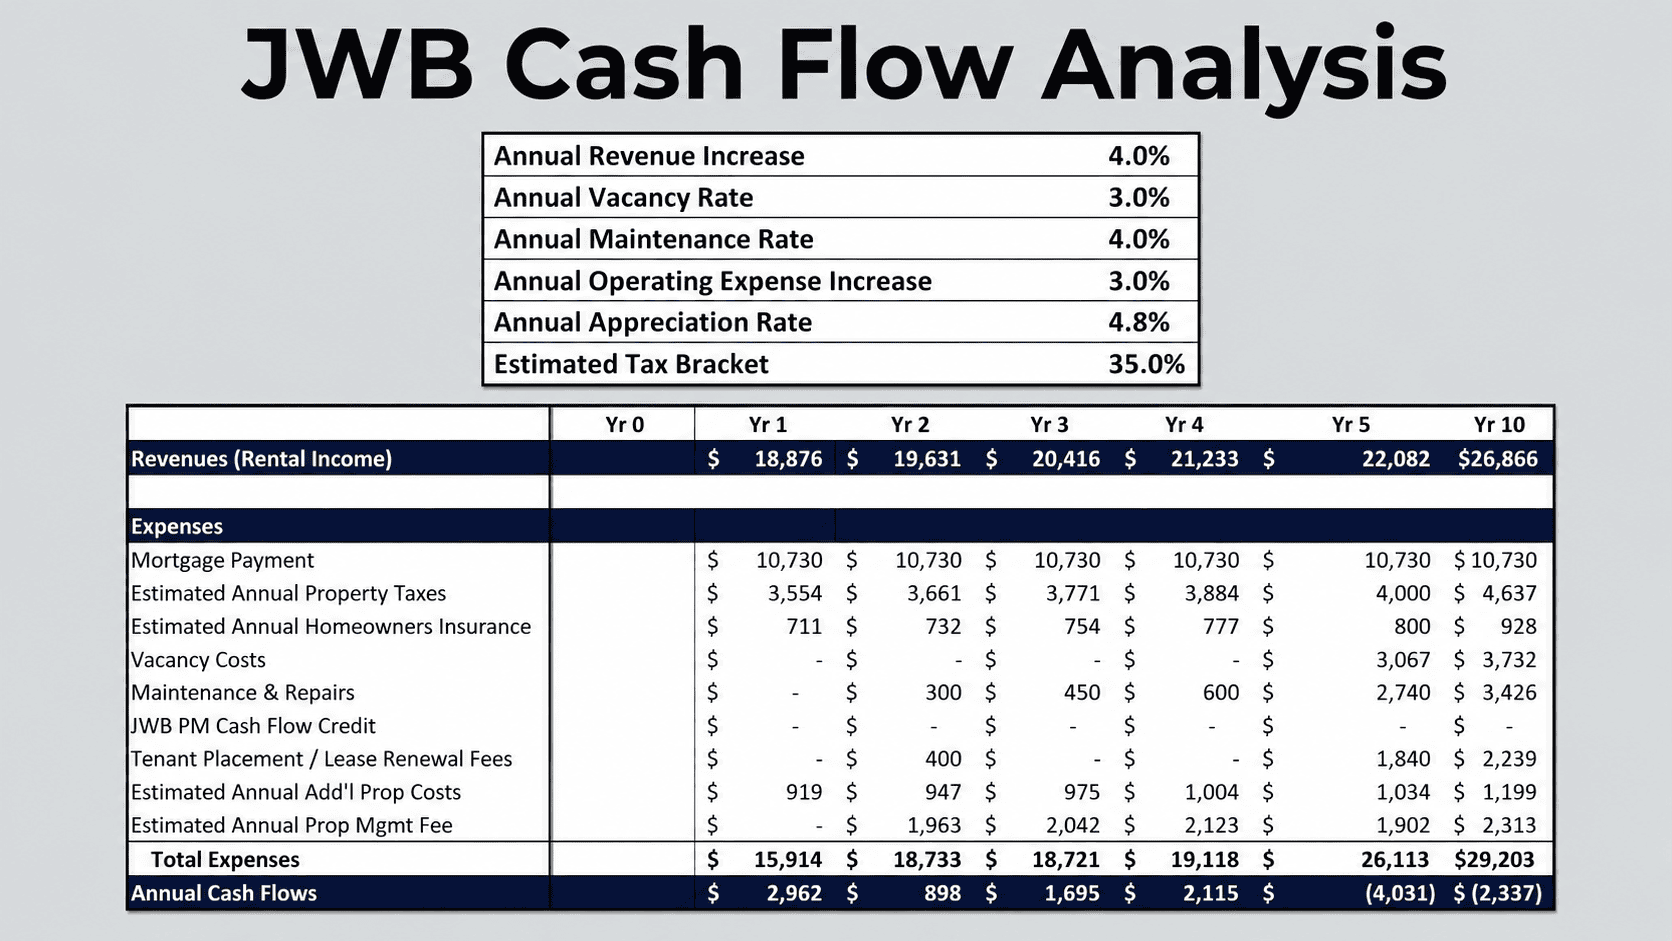
Instead of spreading vacancy evenly across every year, it showed about $3,067 of vacancy in year five, around the time a resident turn would reasonably be expected.
Maintenance followed the same idea, with about $2,740 in year five when the property turned.
That creates a bumpier projection, but after watching thousands of rental homes operate over the years, that pattern makes sense.
Residents move. Repairs happen. Some years cost more than others.
So when a maintenance or vacancy assumption shows up on a pro forma, it is worth asking what real operating experience produced that number.
NOT YOUR AVERAGE INSIGHT: You Want To See The Bumps
👇 What real rental property behavior looks like
The most useful pro forma is one where the headline return can be traced back to something understandable.
- What created the number?
- When is the projected value expected to show up?
- Which assumptions come from actual operating history, and which depend on what happens in the market?
A pro forma cannot tell us exactly what the next ten years will look like. We shouldn’t expect it to.
What matters more is whether it gives us a reasonable picture of what ownership could look like, including the bumps, with assumptions that someone can clearly explain.
That is why we can spend less time asking, “What return does this property show?” and more time asking what sits underneath it.
The return gets our attention. The assumptions tell us whether the story makes sense.
Just remember… Don’t Be Average.
Gregg Cohen
Co-Founder, JWB Real Estate Capital
Connect with the JWB team!
Let’s discuss how your capital can help create more quality housing and opportunity while working toward your financial goals. Book a no-obligation call today.

As Co-Founder of JWB Real Estate Companies, Gregg Cohen has led the firm’s growth from its early days to serving more than 1,700 clients worldwide, with over $1.3 billion in assets under management. Today, JWB helps everyday investors build passive income through single-family rental properties and manages a portfolio of more than 7,000 homes, primarily across Northeast Florida.
Since 2020, JWB has invested $60M+ in downtown Jacksonville, owning about 25 city blocks and driving community growth and investor returns.
Cohen is an Ernst & Young Entrepreneur of the Year (Florida) and co-host of “The Not Your Average Investor Show.”
Listen to our podcast!
Check out our top-rated Not Your Average Investor Show, packed with news, insights and how to build generational wealth.
Dedicated to creating opportunities to welcome our neighbors home.
$1,000,000 RAISED
Listen to our podcast!
Check out our top-rated Not Your Average Investor Show, packed with news, insights and how to build generational wealth.
Dedicated to creating opportunities to welcome our neighbors home.