
If you’re building wealth for retirement, you’ve probably asked: How much do I need to save?
But there’s another question worth asking: What if the bigger advantage is how early you start… and what you eventually own?
That’s what caught my attention about a new type of investment account being introduced for children. Officially called Trump Accounts, they give the youngest Americans an opportunity to start investing from birth and potentially benefit from decades of compounding.
The politics aren’t what interest me. The math does.
Because this idea raises a much bigger question about how we build wealth in America.
Retirement balances are higher than ever, yet confidence in retirement remains near historic lows.
So maybe the goal isn’t just building a bigger pile of money.
Maybe it’s about starting earlier and building assets that can eventually produce income.
Let’s dive in.
What $100 a Month Can Become
The newly passed “Trump Accounts” allow families to contribute up to $5,000 per year into tax-deferred accounts for kids under 18, with the federal government even seeding $1,000 for children born between 2025 and 2028.
We always talk about the power of compound interest, but we rarely get to see what happens when you start at day zero. Look at how small, early contributions snowball over a child’s lifetime:
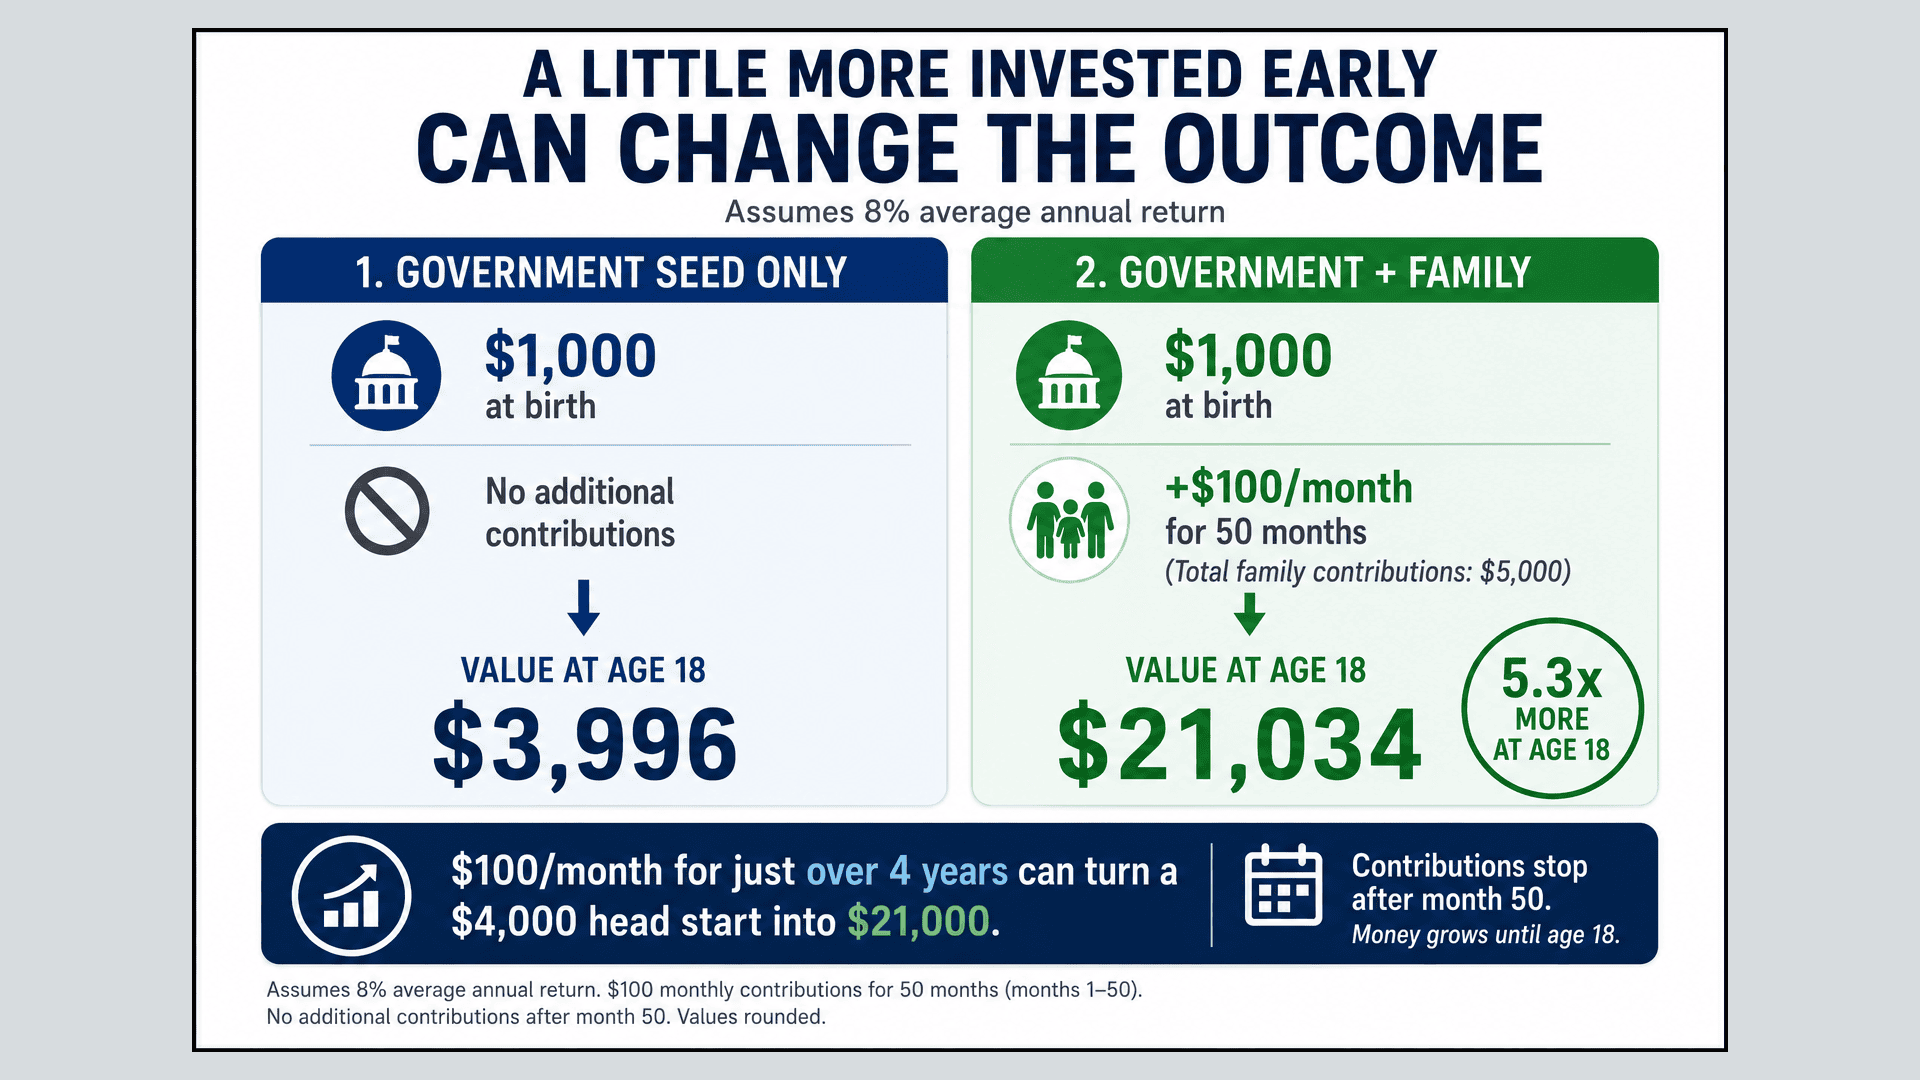
- The $100/Month Approach: If a family puts away just $100 a month for 50 months ($5,000 total) before a child turns five, that money grows to ~$21,000 by age 18.
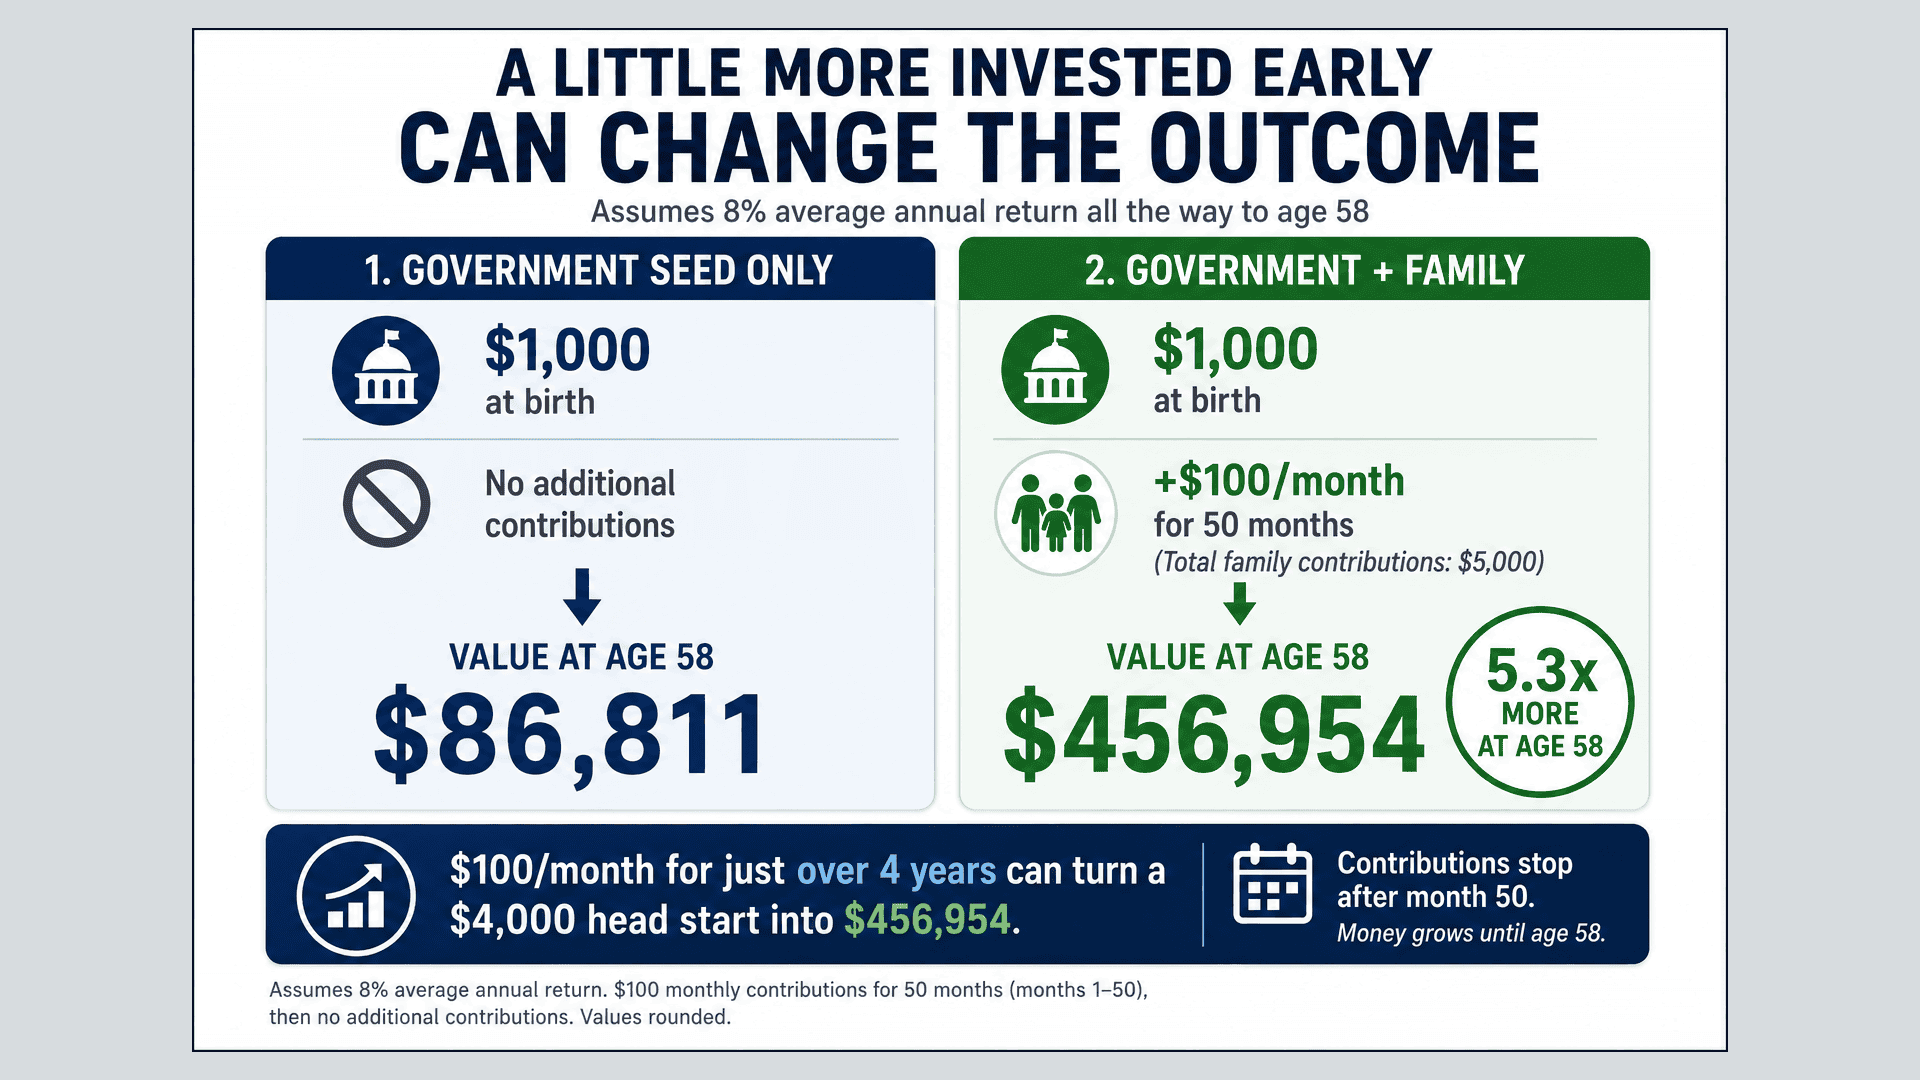
- The Long-Term Compound Effect: If you let that same ~$21,000 sit and compound without adding another dollar, it grows to $456,954 by age 58. That’s nearly half a million dollars created from a few years of skipped tchotchkes.
- The Maxed-Out Approach: If you max out the $5,000 limit every year through age 18, your child steps into adulthood with roughly $206,000 sitting in their account.
Starting early gives our kids a massive head start, but it only fixes one part of the retirement equation.
The Problem With “Just Save More”
Right now, our country is caught in a massive retirement contradiction…
“We’ve never had more money sitting in our retirement accounts, yet we’ve never felt less confident in our ability to actually retire comfortably.”
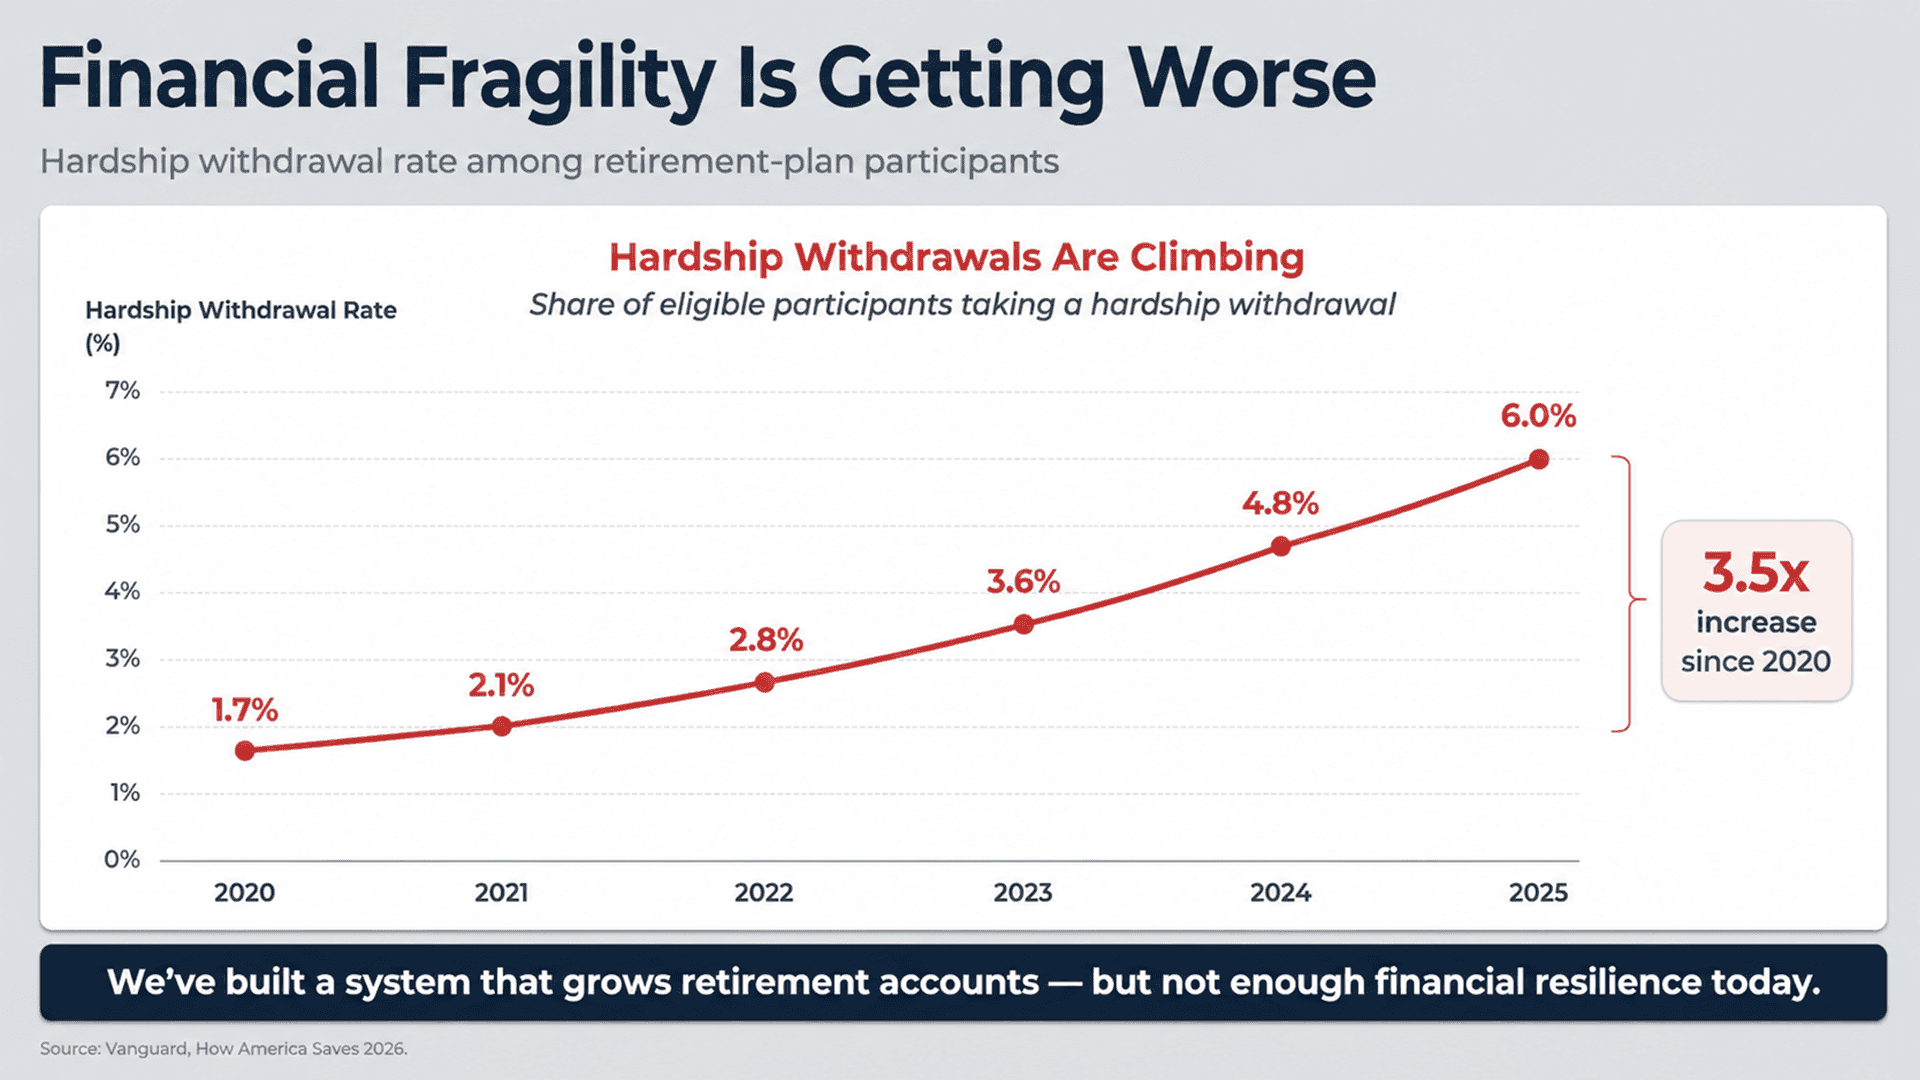
The latest Vanguard data shows that 401(k) participation, savings rates, and account balances are all climbing. On paper, we are winning. But behind those numbers, hardship withdrawals, where people pull money out early just to survive daily financial stress, have spiked 3.5 times higher than in 2020.
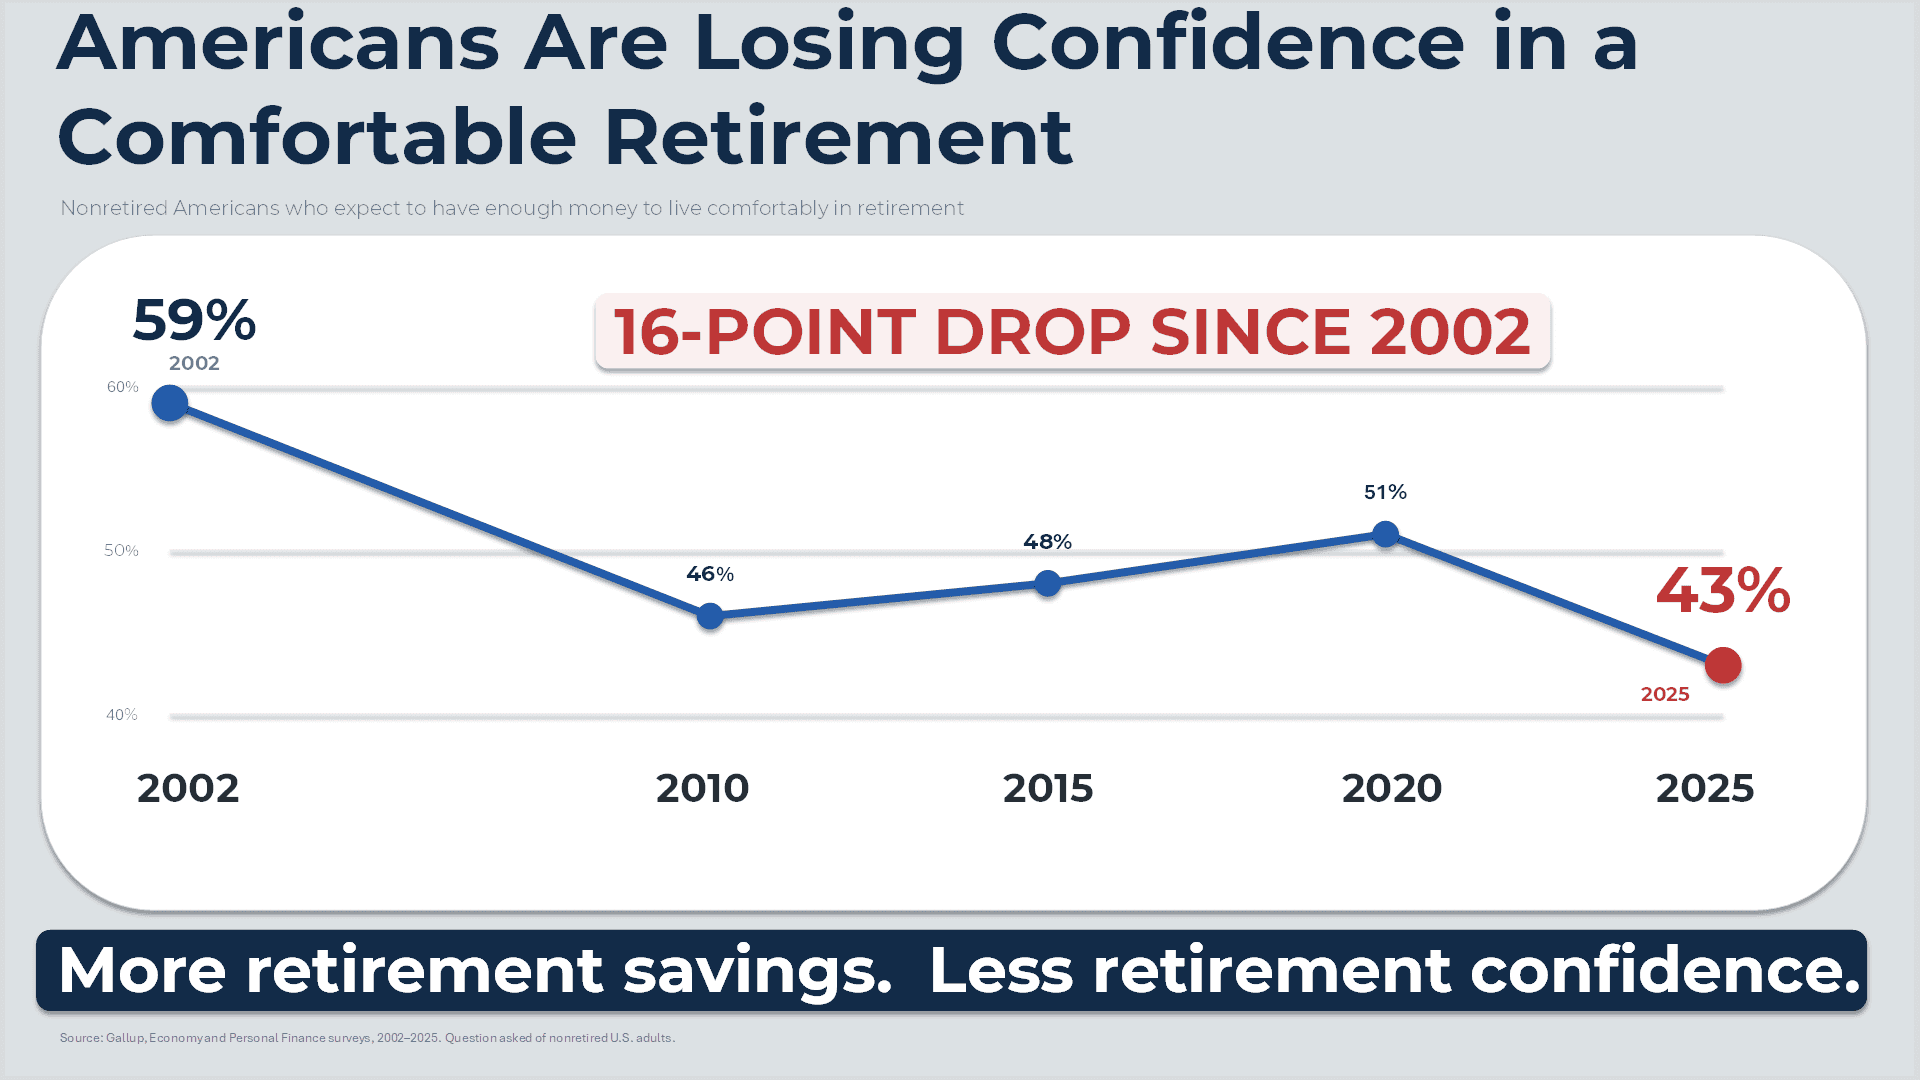
Gallup polls show that only 43% of Americans feel secure about retirement, down from 59% two decades ago.
👇 Why bigger balances don’t always mean greater retirement confidence
Retirement planning has traditionally focused heavily on accumulating enough net worth to support spending later in life. That approach has helped millions of people build wealth on paper. But the data raises another question: should retirement planning also consider how much ongoing income our assets have the potential to produce?
That doesn’t mean we stop saving. It means we can broaden the conversation beyond how much we accumulate to also consider what our assets have the potential to produce.
|
Retirement Model: Net Worth Portfolio |
Retirement Model: Income-Producing Portfolio |
| Focuses on growing your net worth over time. | Focuses on creating assets that can produce ongoing income. |
| Eventually, some accumulated assets may need to be converted into spending. | Assets can produce income while you continue to own them. |
| Retirement planning often centers on how much you’ve accumulated. | Retirement planning can also center on how much income your assets can produce. |
NOT YOUR AVERAGE INSIGHT: Own Something That Outlives You
For generations, retirement planning has largely centered on accumulating a big enough nest egg to support us later in life.
But as we saw in the Vanguard data, bigger balances haven’t translated into greater peace of mind.
That raises an interesting question: What if we measured retirement readiness not only by how much we’ve accumulated, but also by how much income our assets have the potential to produce?
- Trump Accounts show the potential impact of starting early and giving compounding more time to work.
- 401(k) trends remind us that a growing account balance and confidence about retirement aren’t necessarily the same thing.
- Rental properties give us one example of an income-producing asset – one with the potential to generate cash flow while also building equity over time.
Maybe retirement planning doesn’t have to be solely about accumulating enough to eventually spend down. It can also include thinking about the assets you want to own—and what you want those assets to produce – for you and the generation after you.
Just remember… Don’t Be Average.
Gregg Cohen
Co-Founder, JWB Real Estate Capital
Connect with the JWB team!
Let’s discuss how your capital can help create more quality housing and opportunity while working toward your financial goals. Book a no-obligation call today.

As Co-Founder of JWB Real Estate Companies, Gregg Cohen has led the firm’s growth from its early days to serving more than 1,700 clients worldwide, with over $1.3 billion in assets under management. Today, JWB helps everyday investors build passive income through single-family rental properties and manages a portfolio of more than 7,000 homes, primarily across Northeast Florida.
Since 2020, JWB has invested $60M+ in downtown Jacksonville, owning about 25 city blocks and driving community growth and investor returns.
Cohen is an Ernst & Young Entrepreneur of the Year (Florida) and co-host of “The Not Your Average Investor Show.”
Listen to our podcast!
Check out our top-rated Not Your Average Investor Show, packed with news, insights and how to build generational wealth.
Dedicated to creating opportunities to welcome our neighbors home.
$1,000,000 RAISED
Listen to our podcast!
Check out our top-rated Not Your Average Investor Show, packed with news, insights and how to build generational wealth.
Dedicated to creating opportunities to welcome our neighbors home.